Introduction
Most people today are skeptical of bitcoin because they were born into a ‘fiat’ system. They believe ‘money’ is only legitimate when issued by the government and designated as ‘legal tender’. Most don’t question the sustainability, economics, or ethics of such a system, and assume that it’s just the natural order of things. But it isn’t. Questioning the status quo requires setting aside all preconceived beliefs and reasoning up from first principles. Only then can a revolutionary money like bitcoin be appreciated for what it is: an emerging, decentralised, global, self-sovereign, and ethical money that respects human rights and points civilisation toward a prosperous and sustainable future.
Below is a summary of these foundational first principles from the previous articles ‘What is Money?’, ‘Austrian Economics’, and ‘Philosophy & Ethics’. Understanding these is a prerequisite for answering the question, “why bitcoin?”
Recap of First Principles
1 – Bitcoin is Engineered Money
For a money to be voluntarily adopted, it must outcompete other ‘monies’ on the basis of its monetary properties. As previously described in ‘What is Money?’, these monetary properties are 1) divisibility, 2) durability, 3) portability, 4) recognisability, and 5) scarcity. For millennia gold was money because it possessed these properties to a greater degree than anything else. Bitcoin, however, is engineered to perfect these properties.
Each bitcoin is constituted of 100 million subunits called ‘satoshis’, which can be further subdivided at any point in the future without affecting bitcoin’s overall supply. Bitcoin is therefore infinitely divisible, enabling it to support an economy of any size whilst always respecting the property rights of its holders.
Since bitcoin itself is a decentralised distributed network, no single actor can feasibly destroy it. Likewise, unlike commodity monies which can spoil or rust, bitcoin is immaterial and not subject to decay. Bitcoin is therefore perfectly durable, both in the sense that it cannot be unilaterally shut down, and does not physically deteriorate.
Bitcoin is non-physical and can therefore be stored and transmitted as easily as information itself. This allows transactions to occur across any distance, virtually instantly, and without the movement of matter. Bitcoin is therefore completely portable.
Unlike gold, beads, shells, and even fiat currency, bitcoin is impossible to counterfeit. Any bitcoin received to a bitcoin address is pre-authenticated and automatically validated by the consensus of decentralised bitcoin nodes and miners. As such, there is no need for the individual to determine the provenance of any bitcoin they receive. Bitcoin is therefore definitively recognisable.
Unlike any historical money, bitcoin’s total supply is both known, and mathematically hard-capped at 21 million coins. Furthermore, its monetary policy is upheld by consensus meaning nobody can unilaterally issue more for themselves and inflate the supply. Bitcoin is therefore the first money that has knowable and absolute scarcity.
Because bitcoin perfects the 5 monetary properties, it can be expected to perform the 3 monetary functions better than any historical money: 1) store of value, 2) medium of exchange, and 3) unit of account. As bitcoin appreciates, more individuals will choose to store their value in it. Those who do will increasingly prefer to receive bitcoin in exchange for goods and services. When enough people denominate their prices in bitcoin, it will become the unit of account. As network effects grow and liquidity deepens, price appreciation will continue, further highlighting bitcoin as the ideal savings vehicle. This monetisation cycle will accelerate until bitcoin is globally adopted as money.
2 – Bitcoin Solves Gold’s Physicality
Despite its long history as sound money, gold has one major weakness; its physicality. Being physical not only limits gold’s usefulness as money, but it also exposes it to centralisation and state capture. Bitcoin solves for this weakness.
Precious though it might be, nobody knows the actual quantity of gold on Earth. New gold deposits are regularly discovered, and constant innovations increase mining yields by approximately 2% each year. As more gold is mined, the scarcity of above-ground ounces is diluted, impairing its store of value function. Although gold seems to appreciate in fiat terms, it nevertheless loses value in real terms with every additional ounce mined. This makes gold an imperfect store of value as its scarcity is unknown and it’s still subject to supply inflation.
Gold’s mass makes it slow, cumbersome, and risky to trade with, especially over long distances. Its limited divisibility renders it an imprecise medium of exchange, and its authenticity is difficult to verify without bulky and often expensive tools. Furthermore, gold’s density and vulnerability to theft limits its portability, and adds friction and cost to trade. Gold’s performance as a medium of exchange is therefore limited by its divisibility, recognisability, and portability.
Gold’s physical nature makes it easy to steal and therefore expensive to protect. While third-party custodians (banks) emerged to safeguard peoples’ gold, they also introduced counterparty risk and engaged in fractional-reserve banking. This practice facilitated the consolidation of power, the progressive corruption of governments, and the advent of fiat currencies. Whether through bank failures, financial crises, and hyperinflation events, gold’s centralisation and subsequent usurpation has plunged countless millions into poverty.
Because bitcoin is digital it can be engineered to have absolute, knowable, and verifiable scarcity. Its monetary policy is transparently enshrined in open-source code, and its fundamental rules are governed through consensus rather than individual discretion. With zero mass bitcoin can also travel at the speed of information and facilitate transactions across any distance for negligible cost. And its cryptographic security and privacy enables individual self-custody without the need for counterparty risk or centralisation. By solving for gold’s physical flaws, bitcoin can better perform the store-of-value and medium-of-exchange functions of money. Crucially, bitcoin’s ease of self-custody and resistance to theft encourages decentralisation and therefore reduces the risk of state capture. For these reasons, among others, gold has depreciated in bitcoin terms by over 99.9% since bitcoin began trading.
3 – Bitcoin Solves Fiat’s Corruptibility
By imposing a fiat currency and decoupling it from its original backing (eg. gold), governments and central banks acquire enormous amounts of power. In 1887 Lord Acton famously wrote ~ “power tends to corrupt, and absolute power corrupts absolutely”. He observed that unchecked power creates irresistible incentives for corruption and abuse, even among otherwise admirable individuals. In the case of fiat currencies, this manifests in numerous ways.
Fiat currencies typically have only one issuer (the state or central bank) making their governance highly centralised. This places monetary policy in the hands of politically privileged insiders, who are most insulated from negative consequences, and whose interests may not align with society. When immense power centralises without sufficient accountability, incentives tend toward personal gain over furthering civilisation. This initiates a downward spiral of increasingly opaque government, oppressive policy creep, and state corruption. As Mayer Amschel Rothschild once said ~ “permit me to issue and control the money of a nation, and I care not who makes its laws.”
When those in power are insulated from accountability, governments become progressively less trustworthy and their policy directions more unpredictable. For example, broken election promises and misleading interest rate signals make planning for the future significantly harder for individuals and businesses. Neither the politicians nor the central bankers suffer for their infidelities, yet anyone who made financial decisions on false information do. This lack of clarity impairs the cause-and-effect analysis necessary to enable responsibility and rational course corrections. When decision making and reorientation are structurally impeded society becomes increasingly reactive and drawn toward short-term speculation, rather than to sound long-term investments.
In a fiat economy the government holds both the monopoly on currency issuance and the monopoly on violence, threatening the natural human rights to life, liberty, and property. If, for example, a political dissident must earn, transact and pay taxes in fiat currency, then their government need only ‘de-bank’ them and freeze their credit to threaten their livelihood. In this manner, fiat currency can become a powerful coercive weapon of public compliance, which also threatens the right to liberty. Furthermore, by arbitrarily debasing their fiat currencies, governments appropriate wealth from even the ‘law-abiding’ citizens through inflation, thereby violating their right to property.
In an economy running on bitcoin, the privilege to print money is removed, levelling the playing field for all members of society. Bitcoin’s monetary policy is hard-coded and enforced by a consensus of private nodes distributed throughout the world. No single node has the power to unilaterally change bitcoin’s supply, issuance schedule, or other consensus rules which govern its protocol. This removes a crucial avenue for power consolidation among those with political privilege, and instead redistributes power back to the individual. In this manner bitcoin may drive politicians’ incentives to align more with the collective will of the citizens, while increasing political accountability.
As the incentives of government align with society, policymaking becomes more transparent and public officials become more accountable to the people. With less incentive to deceive or mislead the public, governments become more efficient, more benevolent, and more predictable. This increased predictability affords individuals, families, and businesses a greater ability to plan for the future, make capital purchases, and commit to longer term investments. Greater predictability also reduces the opportunity costs of making economic decisions, thereby reducing the input costs of goods and services. When people and businesses can plan, accumulate capital, make better investments, and reduce costs, an upward spiral of increased productivity, abundance, and living standards is initiated, furthering civilisation.
In a bitcoin-based economy, governments would lose their monetary monopoly and much of their ability to weaponise financial infrastructure as a means of coercion. Since bitcoin is permissionless and requires no bank, anybody can create a wallet and transact without third-party approval. It is also censorship-resistant, meaning no central authority can unilaterally prevent or reverse a valid transaction. Together, these properties reduce the effectiveness of de-banking, account freezes and transaction censorship as tools of control, strengthening the individual’s rights to life and liberty. Finally, because bitcoin’s supply cannot be arbitrarily expanded, governments cannot extract seigniorage through monetary debasement. This removes a major mechanism of inflationary wealth transfer, thereby strengthening the individual’s right to property.
4 – Bitcoin is ‘Anti-Fragile’
For an emerging money to displace an incumbent currency, it must be resilient, adaptable and secure. Bitcoin achieves this through anti-fragility: the ability to not only withstand external shocks, but adapt and become more resilient because of them.
Bitcoin derives redundancy from its highly decentralised architecture. Tens of thousands of nodes and globally distributed miners ensure there is no single point of failure that could compromise the network. This geographic dispersion also makes even nationwide bans or internet outages unlikely to threaten bitcoin’s overall survival. Furthermore, self-custody enables individuals to secure their bitcoin without relying on centralised custodians, reducing both counterparty risk and the potential for fractional-reserve banking. Finally, coordinated attempts to shut down nodes, ban mining or restrict self-custody only accelerate the development of countermeasures, which strengthens the network and drives further adoption.
Bitcoin derives adaptability from its open-source development, distributed governance and adversarial testing. Anyone can inspect its code or propose changes through Bitcoin Improvement Proposals (BIPs), which are openly scrutinised by developers, researchers and other network participants. Promising proposals may be implemented in Bitcoin software, but adoption remains entirely voluntary, with node operators, miners, exchanges and users choosing whether to upgrade. Changes to Bitcoin’s consensus rules therefore cannot be imposed by any person, company or government, but must achieve sufficient voluntary adoption across the network. This makes bitcoin adaptable enough to respond to unforeseen challenges, yet conservative enough to ensure that only the most necessary and sound changes are incorporated.
Finally, bitcoin’s Proof-of-Work system creates asymmetric economic incentives that reward participants for securing the network while making attacks prohibitively expensive. Miners compete to add new blocks of transactions by expending real-world energy and computational work, with successful miners receiving bitcoin as a reward. Conversely, an attacker attempting to rewrite a prior transaction must reproduce the accumulated Proof of Work and compete against the continuing work of the honest network, requiring enormous expenditure on specialised hardware and energy with no guarantee of success. The older a transaction gets, the deeper it is buried within the blockchain, making it exponentially more expensive to reverse. Consequently, miners are strongly incentivised to deploy their resources toward securing the network and earning bitcoin rather than attacking it. Proof of Work therefore transforms bitcoin’s security into an economic competition in which honest participation is rewarded while adversarial behaviour is made increasingly costly.
5 – Bitcoin is Economically Sound
Economics is the study of human action in the face of scarcity, and human action is shaped by incentives. Since many of these incentives are influenced by money, the monetary system profoundly affects the prosperity and sustainability of civilisation. Through this lens, economically sound money should incentivise saving, productive investment, responsible credit and fiscal discipline. Bitcoin satisfies each of these criteria to a greater degree than either gold or fiat currency.
Bitcoin’s absolute scarcity, combined with its superior monetary properties, creates the potential for its purchasing power to increase over time. Despite significant volatility, bitcoin’s long-term appreciation has created a powerful incentive to save rather than immediately consume surplus productivity. Saving defers present consumption while increasing future economic security, enabling individuals, families and businesses to plan further ahead and better withstand unforeseen challenges without resorting to debt. Furthermore, when surplus productivity can be reliably carried into the future, individuals are rewarded for producing more than they consume, incentivising greater production and contributing to greater abundance.
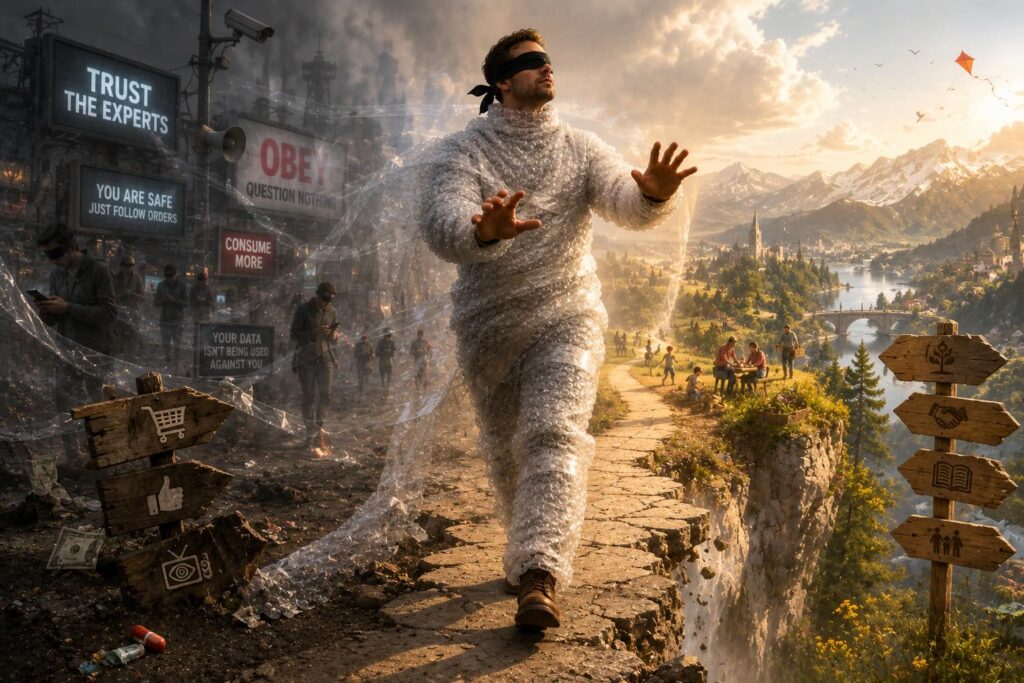
Bitcoin’s propensity to appreciate enables savers to accumulate wealth for larger and longer-term investments, including in capital goods (assets such as tools, machinery and infrastructure that increase future productivity). By investing in capital goods, individuals and businesses can produce more output from the same amount of time, labour and resources. This increased productivity creates greater abundance, allowing prices to fall and living standards to rise. In this way, bitcoin promotes capital formation, which expands society’s productive capacity and generates lasting economic wealth.
In a bitcoin-based economy, new money cannot simply be created to facilitate ever-expanding credit. Lending would therefore face a harder constraint from real savings and available capital, making credit scarcer and more appropriately priced. Interest rates would emerge through natural price discovery, rising when savings are scarce or demand for credit is high, and falling when capital is plentiful relative to demand. Higher rates naturally discourage investments whose expected returns cannot justify their cost of financing, reducing incentives for excessive leverage and malinvestment. Furthermore, as available credit becomes scarce, borrowers must increasingly compete for capital, placing upward pressure on rates and constraining further borrowing. Bitcoin therefore would naturally regulate credit markets and prevent the unsustainable debt accumulation which characterises fiat economies.
In a bitcoin economy where money cannot be arbitrarily created, governments would face much harder constraints on public spending. Any expenditure would ultimately need to be funded through taxation*, accumulated reserves, or genuine borrowing, rather than through debasement and inflation. This would prevent persistent fiscal deficits, since additional borrowing must compete for scarce capital, putting upward pressure on interest rates, and eventually be repaid or refinanced. Scarcer public funds would increase pressure to eliminate waste, corruption and redundant bureaucracy while directing resources toward programs that deliver the greatest public value. Crucially, if additional public spending were warranted, the government would have to explicitly justify the additional taxes* to the citizens who must ultimately bear their cost. Bitcoin would therefore make government spending harder to conceal or defer, increasing fiscal accountability and encouraging more efficient allocation of public resources.
* in a bitcoin economy, ‘taxation’ would likely give way to other models of citizen contribution, including voluntary subscriptions or user-funded services, rather than coercive extraction.
6 – Bitcoin is Ethically Sound
In ‘Philosophy & Ethics’, responsibility, the natural rights to life, liberty and property, and non-aggression were identified as prerequisites for human flourishing. Therefore, an ethically sound monetary system must align with these principles. Bitcoin does so by reinforcing truth and responsibility, protecting natural human rights, and disincentivising aggression.
Sound money naturally emerges through voluntary exchange. Therefore, for a money to be ethically sound, individuals must be free to adopt or reject it. Bitcoin satisfies this principle because participation is entirely voluntary. Nobody is required by the protocol to acquire, hold or accept bitcoin, and anyone is free to leave the network. Like commodity monies such as shells, salt and gold, bitcoin must therefore compete for adoption on the strength of its monetary properties. It has no issuing authority to mandate its use, and its adoption has instead emerged organically as individuals have chosen to exchange their labour, goods and existing currencies for it. Bitcoin began as an idea, instantiated in open-source code and freely offered to the world. Its continued adoption therefore depends upon people continuing to find it useful.
Conversely, fiat currencies rely heavily on coercion and narrative for their adoption and ongoing use. The ‘legal-tender’ laws, which selectively privilege fiat currencies, are the metaphorical ‘stick’, while the promises of adhering to the ‘social contract’ are the ‘carrot’. By artificially altering the incentives, issuers of fiat currency quietly subvert the meritocratic process of monetary selection, and privilege themselves at the expense of everyone else. Fiat currencies therefore fail the ethical standard of voluntary, impartial money. In short, sound money emerges; unsound money is imposed.
The ethical principle of responsibility requires the relationship between cause and effect to remain sufficiently visible for learning and improvement to occur. Bitcoin reinforces this relationship through transparent and predictable monetary rules. Unlike fiat currencies, whose supply and monetary policy are subject to institutional discretion, bitcoin’s issuance is predetermined, independently auditable and capped at 21 million coins. Governments and central banks would therefore be unable to expand bitcoin’s supply to inflate asset prices, finance expenditure or manipulate interest rates. This would remove a major source of monetary distortion and allow market prices to more directly reflect underlying supply and demand.
Accurate prices provide the feedback individuals and businesses need to allocate scarce resources effectively. When prices emerge through market exchange, profits and losses more clearly reflect economic realities such as scarcity, consumer preferences and competition, rewarding productive decisions while punishing poor ones. This preserves the relationship between economic actions and their consequences, enabling participants to learn, adapt and allocate resources more effectively over time. Bitcoin therefore reinforces economic responsibility by making monetary reality harder to manipulate and its consequences harder to conceal.
Bitcoin offers several protections against threats to an individual’s right to life, arising primarily from its digital nature and fixed supply.
Unlike physical assets such as cash, gold and jewellery, bitcoin cannot generally be stolen through lethal force alone. Access is controlled by ‘private keys’, which can be secured in ways that make theft extremely difficult. Killing a bitcoin holder doesn’t necessarily make their wealth accessible to an attacker, thereby creating an incentive to preserve the victim’s life. Security arrangements such as multi-signature wallets and geographically distributed backups can further reduce the effectiveness of physical coercion.
Bitcoin can also protect those fleeing war or persecution by allowing wealth to be carried as information rather than physical property. Historically, fleeing across borders could require abandoning assets that were immovable, confiscatable or difficult to transport. Wealth stored in bitcoin can instead be memorised if necessary, increasing individual mobility in circumstances where delay could prove life-threatening.
Finally, bitcoin’s fixed supply would constrain the ability of governments to finance warfare through monetary expansion. Wars would instead need to be funded more explicitly through taxation, accumulated reserves or genuine borrowing, making their economic costs more accountable. Constraining war financing also makes it less profitable for hawkish stakeholders and more politically costly for bureaucrats. While this would not eliminate warfare, it could significantly reduce the scale, duration, and frequency of armed conflicts.
In short, bitcoin protects life by making violence less effective for criminals, escape more feasible for those under threat, and large-scale warfare more difficult to finance.
Bitcoin protects the right to liberty through its permissionless, decentralised and borderless design. Unlike the fiat system, anybody can create a bitcoin wallet and transact directly with others without requiring approval from a bank, government or other privileged entity. Because no central gatekeeper controls access, excluding individuals from bitcoin itself is considerably more difficult, removing financial exclusion as a viable tool of state coercion.
Bitcoin’s peer-to-peer design likewise enables individuals to send money across political and national boundaries without fear of an intermediary arbitrarily blocking their transactions. This also strengthens freedom of exit by allowing individuals who self-custody their bitcoin to move their wealth between jurisdictions without requiring the cooperation of a bank. By reducing the effectiveness of capital controls and financial censorship, individuals and their wealth become more mobile. Consequently, governments face competitive pressure to provide conditions under which individuals and capital voluntarily remain.
Finally, bitcoin’s fixed supply prevents governments from financing their expansion through monetary debasement. Greater reliance on explicit taxation and genuine borrowing makes the cost of government more visible and constrains the accumulation of state power. Combined with bitcoin’s permissionless network and global portability, this reduces the effectiveness of financial repression and strengthens the individual’s ability to resist, exit or avoid coercive institutions.
In short, bitcoin protects liberty by making financial participation permissionless, wealth more portable, and monetary coercion more difficult.
Bitcoin protects the right to property through its cryptographic security, non-physical nature and immunity to arbitrary monetary dilution.
Firstly, control over bitcoin is secured by private keys, which authorise outgoing transactions through cryptographic signatures. Without the relevant private key, an attacker cannot validly spend another person’s bitcoin, while invalid transactions are rejected by validating nodes. Provided the keys remain secure, control over bitcoin therefore rests with the holder rather than a bank, custodian or government. In this sense, property rights are enforced by bitcoin’s protocol rather than institutional discretion.
Furthermore, because private keys exist as information, securing bitcoin does not inherently require walls, vaults, guards or other expensive physical infrastructure. Keys can instead be protected using inexpensive arrangements tailored to the individual’s needs, including multi-signature wallets and geographically distributed backups. Bitcoin can therefore be made extraordinarily difficult to steal at relatively little cost, strengthening an individual’s ability to defend their property.
Finally, bitcoin protects against a subtler form of theft: monetary debasement. When new units of fiat currency are created, their earliest recipients gain purchasing power at the expense of existing currency holders, whose savings are diluted through inflation. Bitcoin’s protocol eliminates this mechanism through its predetermined issuance schedule and finite supply of 21 million coins. No government, central bank or other privileged issuer can create additional bitcoin at will, ensuring that a holder’s proportionate share of the monetary supply cannot be arbitrarily diluted.
In short, bitcoin protects property by making wealth difficult to steal, inexpensive to secure and impossible to arbitrarily dilute.
Bitcoin encourages non-aggression by aligning incentives toward mutually beneficial, voluntary cooperation. Aggression, including violence, coercion, theft and fraud, has persisted throughout human history and is unlikely to disappear. Since it cannot be eradicated, it is best discouraged by making violations of others’ natural rights more difficult and less rewarding.
Bitcoin achieves this structurally through its protections of life, liberty and property. As outlined above, its digital nature makes lethal force less effective for stealing wealth, while its fixed supply makes large-scale violence more difficult to finance through monetary expansion. When aggression becomes less effective and more costly, peaceful alternatives such as negotiation, trade and cooperation become relatively more attractive.
Likewise, bitcoin’s permissionless and borderless network protects liberty by allowing people to hold, exchange and transport value without requiring approval from privileged intermediaries. This reduces barriers to voluntary exchange, enabling more people to bring their unique skills and resources to market. As participation expands across national boundaries, so too can the division of labour, global cooperation and economic productivity.
Finally, bitcoin’s cryptographic security and fixed supply strengthen property rights by making wealth difficult to steal and impossible to arbitrarily dilute. When wealth cannot easily be acquired through theft, coercion or monetary debasement, greater reliance must be placed upon voluntary means such as production, trade and negotiation. The same constraint applies to governments, whose inability to create additional bitcoin would increase their reliance on explicit taxation and genuine borrowing, making coercive extraction more visible and costly.
While bitcoin doesn’t eliminate aggression, it changes the incentives under which people operate. By making violations of life, liberty and property more difficult and voluntary exchange more rewarding, bitcoin shifts the economic advantage toward cooperation. Greater cooperation enables deeper markets, increased division of labour and more efficient trade, ultimately supporting widespread prosperity.
7 – Bitcoin Separates Money From State
For most people today, money and government appear inseparable. Yet money does not inherently require a state, central bank or issuing authority. Instead, sound money emerges voluntarily through trade, just as gold did long before fiat currencies existed. Throughout history, however, governments have progressively centralised control over money in order to expand its supply and harness human labour. Bitcoin fundamentally breaks this relationship by replacing the monetary issuer with decentralised consensus and predetermined rules. It allows money to exist independent of political authority, potentially separating money from state for the first time.
Throughout history, states seeking monetary control have often followed a similar progression. First, they borrow credibility from existing sound money, either by minting coins from precious metals or issuing notes redeemable for them. In doing so, they offer people convenience in exchange for trust in the issuer. Once issued, governments typically reinforce demand by requiring taxes and other obligations to be settled in their currency, while disadvantaging competing monies through regulation. After sufficient compliance has been achieved, any original monetary constraints can be relaxed through dilutive alloying of coins, suspension of convertibility or unbacked money printing. For as long as public trust is preserved, the state can steal human labour in perpetuity through the debasement of its currency.
People exchange their finite time and productive effort for money so that its value can be carried into the future. Money therefore represents stored human labour. Controlling its supply gives the state a mechanism for indirectly appropriating the fruits of that labour. By creating new currency, the state and its beneficiaries can acquire real goods and services by transferring purchasing power from existing holders to themselves. Unlike overt confiscation or slavery, this extraction is less conspicuous, appearing instead as rising consumer prices. In this sense, monetary debasement enables the state to steal a portion of human productivity without commanding the labour that produced it, making the transfer less visible and the theft more deniable.
Currency debasement enables governments to command resources far beyond what they can explicitly raise through taxation. This alleviates the need for fiscal discipline, allowing the state to expand beyond what citizens might willingly finance. As control of and proximity to government become increasingly lucrative, incentives for rent-seeking, cronyism and corruption grow, while the expanding public sector parasitises the productive economy. Monetary debasement therefore distorts economic and political incentives, rewarding those who capture state power with unearned access to society’s resources.
As government expands, it consumes more resources, requiring a combination of higher taxation, additional borrowing and further debasement. As more purchasing power is siphoned off by the state, the currency depreciates, causing inflation and discontent. Governments often respond with subsidies, handouts and price controls, but these interventions only introduce new distortions. Price ceilings, for example, create supply shortages and black markets, while subsidies and handouts incur additional fiscal costs. Inevitably, falling confidence in the currency and its institutions can contribute to social unrest, political upheaval and regime collapse. History provides striking examples of this progression, including ancient Rome, Song China, Revolutionary France and Weimar Germany.
An early example is the progressive debasement of Roman silver coinage. Under Augustus, the denarius contained roughly 95-98% silver, but Nero began diluting its purity around 64 AD, a practice continued by later emperors. As military and political ambitions grew, successive debasement allowed the state to extract greater spending power from its precious-metal reserves, until the late third century when coins contained only traces of silver. This debasement contributed to the Crisis of the Third Century (235-284 AD), a period of severe inflation, civil war and political instability. Emperor Diocletian later attempted to suppress rising prices through his Edict on Maximum Prices in 301 AD, only to exacerbate shortages and fuel black markets. Rome therefore illustrates a recurring pattern: political ambitions incentivise monetary debasement, leading to inflation and economic instability, and inviting counterproductive interventionist policies.
The invention of paper money in Song China removed much of the physical constraint that metallic coinage placed on monetary debasement. Around 1023 AD, the Northern Song established the jiaozi, a state-issued paper currency initially subject to issuance limits and supported by coin reserves. However, as fiscal and military demands grew, these constraints were repeatedly exceeded, leading to inflation. After the Jurchen conquest ended the Northern Song in 1127, the Southern Song introduced the huizi, whose issuance constraints were likewise progressively relaxed, resulting in severe inflation. Following the Mongol conquest in 1279, Kublai Khan’s Yuan Dynasty imposed yet another currency, its paper chao, while restricting the monetary use of precious metals. Again, the chao suffered inflation due to unbacked issuance. China thus demonstrates that once currency can be decoupled from sound money, the political incentives repeatedly favour debasement at the expense of economic stability.
An acute example occurred during the French Revolution. Following the Crown’s debt crisis in 1789, the revolutionary government confiscated Church lands and issued paper assignats against them. Initially interest-bearing and land-backed, the assignats were later transformed into legal tender and increasingly printed to finance government expenditure. As inflation accelerated, authorities imposed severe penalties for refusing or discounting them, while also enforcing price controls through the Law of the Maximum in 1793. This ultimately failed, contributing to shortages and black markets, and debasement continued until the assignat hyperinflated into worthlessness. Its replacement, the mandat territorial, was likewise debased and rapidly suffered a similar fate. The resulting monetary collapses devastated savings and creditors before stability was eventually restored through a bimetallic (gold/silver) standard under Napoleon in 1803. Revolutionary France therefore demonstrates how monetary debasement can lead to inflation, coercive enforcement, maladaptive intervention and ultimately currency collapse.
Perhaps the most infamous modern example occurred in Germany between 1914 and 1923. At the outbreak of World War I, the German Empire suspended gold convertibility of the mark and financed much of the war through debt and money printing. Defeat left the Weimar Republic with massive war debts, fiscal deficits and onerous reparations, which the government attempted to resolve by further debasing its currency. In 1923, the resulting hyperinflation led to an exchange rate of 4.2 trillion marks per US dollar, devastating German peoples’ savings and fixed incomes. A monetary reset was attempted via the asset-backed Rentenmark, but the loss of institutional trust lead Germany to rely on Wall Street credit, ultimately exposing it to the American lending collapse of 1929. The resulting Depression, combined with the legacy of war, inflation and political instability, helped create conditions in which political extremism flourished. Weimar therefore demonstrates how monetary debasement can destroy a currency, devastate accumulated savings and contribute to political instability.
Human history demonstrates a recurring vulnerability: once states control money, they acquire both the ability and incentive to debase it. The United States represents the modern culmination of this pattern. Its first paper currency, the Continental, was issued in 1775 and its acceptance compelled in some states with severe penalties. However, its over-issuance ultimately caused it to collapse, leading to social unrest and the phrase “not worth a continental”. The Constitution subsequently prohibited states from making anything but gold and silver coin legal tender, but imposed no such restriction on the federal government. During the Civil War, the federal government issued more than $450 million in paper greenbacks and made them legal tender through the Legal Tender Acts. The Federal Reserve Act of 1913 then further centralised monetary power and established a federally managed “elastic currency.”
Once federal monetary control was established, gold’s remaining constraint was progressively removed. In 1933, Roosevelt’s Executive Order 6102 compelled citizens to surrender their gold for dollars at $20.67 per ounce, or face up to 10 years’ imprisonment and a $10,000 fine. The government subsequently repriced gold to $35 per ounce, devaluing all dollars by approximately 41%. In 1944, the Bretton Woods Agreement promised foreign governments gold convertibility at $35USD/oz while their currencies were pegged to the dollar. However, continued US monetary expansion progressively weakened the dollar, prompting foreign central banks to redeem dollars for gold. Nixon responded by suspending gold convertibility in 1971, severing the dollar’s final link to gold. Since then, the US money supply has exceeded $23.22 trillion (July 2026), causing the dollar to lose over 97% of its value relative to gold. The United States now operates a purely fiat currency with no convertibility, commodity backing or fixed supply constraint.
Given its extraordinary monetary expansion, why hasn’t the dollar already collapsed? Unlike previous fiat currencies, the dollar’s ‘world reserve currency’ status, cemented through Bretton Woods, has created enormous foreign demand for dollars and dollar-denominated assets. This effectively expanded the population of dollar holders, allowing the United States to continue printing money to pay for foreign goods and services. However, its ability to perpetually export inflation to the world depends upon continued global faith in the dollar. If individuals, businesses and governments increasingly migrate toward sound money, such as bitcoin, falling dollar demand could cause global demand for dollars to collapse. Despite its current dominance, the US dollar is not immune to hyperinflation; its fate has merely been delayed by globalising the economic base across which its debasement can be absorbed.
Because money is essential to large-scale human cooperation, its soundness has profound ethical consequences. When the state monopolises money, it restricts monetary choice and therefore individual liberty. When it debases that money, it silently steals the purchasing power of its citizens, violating their property rights and enriching politically privileged groups with the fruits of others’ labour. As previously argued, this concealed appropriation represents a subtle form of slavery that concentrates wealth and power while obscuring the extraction itself. At its extreme, monetary collapse can also threaten life through shortages, starvation, violence and social breakdown. State control over money therefore threatens all three natural human rights to life, liberty and property. Since these rights form the ethical foundation of peaceful civilisation, their systematic violation progressively undermines civilisational stability and have historically culminated in collapse, revolution or tyranny.
So how does bitcoin separate money from state? Whereas previous monetary reforms replaced one privileged issuer with another, bitcoin eliminates the issuer altogether. Its decentralised rules, absolute scarcity and globally distributed Proof-of-Work network prevent any government or institution from unilaterally expanding its supply or extracting seigniorage from its issuance. With no issuer to capture, bitcoin instead monetises from the bottom up as individuals voluntarily adopt it as a store of value, medium of exchange and ultimately unit of account. This is how sound money emerges: through voluntary market convergence upon superior monetary properties rather than coercion. As adoption grows, value can migrate from fiat currencies into bitcoin, weakening the extractive power states derive from controlling currency issuance. Governments may resist through regulation, capital controls and financial repression, but cannot unilaterally alter bitcoin’s supply or prevent its adoption globally. For the first time, monetary reform can occur organically, without any monetary authority, and on a global scale.
As bitcoin adoption grows, governments unable to fund themselves through currency debasement would become increasingly reliant on explicit taxation and genuine borrowing. Making the cost of government more transparent would impose greater fiscal discipline, placing pressure on waste, corruption and inefficient bureaucracy while increasing accountability to those funding it. Greater fiscal constraint could also expose poorly delivered public services to competition from private alternatives, reducing the resources and functions controlled by the state. Meanwhile, without inflation continually offsetting productivity gains, technological progress could express itself naturally through falling prices. Individuals could therefore retain more of their purchasing power while goods and services become cheaper. This would raise living standards and enabling longer-term planning, stronger families and communities, and more meaningful pursuits.
Contrary to the vicious cycle of monetary debasement and societal erosion enabled by fiat currencies, bitcoin creates a virtuous cycle of aligned incentives, individual responsibility and voluntary cooperation. Its decentralised rules eliminate the privileged issuer, protecting the fruits of human labour and imposing greater fiscal discipline on governments. Individuals are consequently better able to save, invest and plan further into the future, promoting capital formation, productivity and abundance. Bitcoin therefore offers humanity an escape from the recurring cycle of monetary capture, debasement and political exploitation. Just as the printing press weakened the monopoly over information and enabled the separation of church and state, bitcoin weakens the monopoly over money and may ultimately drive the separation of money and state.
8 – Bitcoin Promotes Civilisation
Civilisation emerges through voluntary cooperation, division of labour and exchange, enabled by sound money that supports saving, capital formation and rising productivity. Yet history repeatedly shows sound money becoming centralised, captured and debased, progressively corrupting the incentives upon which civilisation depends. Bitcoin offers something historically unique: a money resistant to capture and impossible to debase. What might this mean for individuals, markets, communities, political order and civilisation itself?
Bitcoin’s finite supply and resistance to monetary debasement make it a potential long-term store of value. Combined with its monetary properties and growing network effects, this creates an incentive to save rather than immediately consume, preserving future optionality and expanding an individual’s economic time horizon. Greater savings support capital formation, increasing productivity, abundance and living standards. Growing prosperity enables longer-term planning, stronger families and greater intergenerational thinking, which strengthen the communities upon which civilisation depends. By rewarding saving, bitcoin therefore incentivises present sacrifice for future prosperity rather than sacrificing the future for present consumption.
In a fiat economy, proximity to the money printer is rewarded through the ‘Cantillon effect’; where the earlier one receives the newly created currency, the more they can benefit from its debasement. This incentivises cronyism, regulatory capture, and rent-seeking, while enabling subsidised leverage, bailouts and price distortions in markets. None of this promotes a healthy or sustainable civilisation. Conversely, bitcoin removes money printing altogether, shifting economic incentives back toward competitive value creation. When monetary privilege is no longer available, wealth must instead be earned through voluntary exchange. As free market competition ensues, profits reward those who add value to scarce resources, while losses expose capital misallocation and allow resources to migrate elsewhere. Bitcoin therefore strengthens free-market meritocracy by shifting incentives toward value creation, improving resource allocation, and enabling greater abundance through productivity.
Currency debasement penalises cash savers by eroding their purchasing power, and drives individuals to purchase scarce assets such as property and equities to preserve wealth. This store-of-value demand adds a ‘monetary premium’ beyond an asset’s underlying utility or productive value. In housing, this can inflate prices far beyond their value as shelter, reducing affordability and attracting further speculation. In financial markets, monetary premiums can similarly inflate valuations and direct capital toward more leveraged or speculative investments rather than genuinely productive enterprises. Such misallocation reduces economic efficiency by diverting scarce capital from more productive uses. Bitcoin offers an alternative by restoring the store-of-value function to money itself. If wealth can be reliably preserved in money, individuals have less need to monetise houses, equities and other scarce assets. This would reduce monetary premiums and allow prices to more accurately reflect an asset’s underlying utility. When housing affordability, capital allocation and economic output are improved, the foundations of civilisation are strengthened.
Fiat monetary expansion is often achieved by suppressing interest rates below what the free market would otherwise support. This artificially incentivises borrowing, leverage and speculation while driving up consumer prices and asset valuations. Rising asset prices can then justify further borrowing, creating a self-reinforcing cycle of leverage and malinvestment that leaves the economy vulnerable when credit conditions are tightened. As discussed in ‘Austrian Economics’, the manipulation of interest rates is a fundamental contributor to the boom-bust cycle that characterises fiat economies. When interest rates are eventually raised, the resulting deleveraging can trigger liquidations, capital destruction, unemployment and recession. Unlike fiat currencies, bitcoin cannot be printed to artificially expand the monetary base or suppress market interest rates. In a bitcoin-based economy, lending would therefore face meaningful constraints and interest rates would be determined by natural price discovery. Scarce credit would raise borrowing costs and discourage marginal investments, while abundant savings would lower them. This self-regulating effect would naturally reduce leverage and malinvestment, leading to greater financial stability, improved economic security and a more resilient civilisation.
Monetary debasement relaxes the fiscal constraints on government, enabling political power to expand, centralise, and foster corruption that increasingly rewards those in proximity to the state. Bitcoin removes that funding mechanism altogether, forcing governments to rely more on explicit taxation and genuine borrowing. This limits state expansion and encourages smaller, more decentralised governance, where decision-makers are closer to the communities they serve and therefore more accountable. Bitcoin’s global portability would also incentivise governments to attract rather than merely extract from productive citizens. As political power decentralises, greater responsibility can also return to individuals, families, churches, neighbourhoods and voluntary organisations, allowing civil society to reclaim functions previously absorbed by the state. By fixing the money, bitcoin could therefore decentralise power itself, shifting responsibility away from decaying and bloated institutions toward individuals and their communities.
Today, the global economy is fragmented across national currencies, creating monetary frictions that make trade and capital flows dependent upon intermediaries, foreign exchange infrastructure and political permission. These barriers impede international exchange and create opportunities for political corruption and rent-seeking. In this sense, nation states can resemble legalised cartels, where the global economy is partitioned into protected jurisdictions where political access confers economic advantage. Bitcoin offers an alternative: an open, permissionless and globally interoperable monetary network requiring no central political authority. As global money, bitcoin could reduce monetary barriers to cross-border trade and investment, allowing capital to flow more readily toward productive opportunities and enabling businesses to access deeper international markets. Better global capital allocation and market participation would increase productivity while deepening the international division of labour. Greater economic interdependence also raises the opportunity cost of conflict by making peaceful cooperation increasingly valuable. Bitcoin could therefore promote global productivity, cooperation and peace by providing a neutral monetary foundation for voluntary exchange across political borders.
Individuals are the fundamental units of civilisation, and their collective actions are shaped by the incentives they face. Because money coordinates all economic activity, its incentives profoundly influence the trajectory of civilisation. Unlike fiat currency, bitcoin rewards saving, long-term thinking, and meritocratic value over proximity to the state. It also reduces forced speculation, monetary premiums and misallocaiton of capital. Naturally-discovered interest rates further constrain leverage and malinvestment, while firmer fiscal limits encourage smaller, more accountable and competitive governments. As political power decentralises, responsibilities previously absorbed by the state can return to individuals, families and communities, making society more resilient. Meanwhile permissionless global trade deepens the division of labour and incentivises peaceful interdependence over violence. Bitcoin doesn’t change human nature, but it does change the economic selection pressures under which people operate. By making productive, responsible and cooperative behaviour relatively more rewarding, bitcoin provides an ethical monetary foundation upon which a more peaceful, prosperous and resilient civilisation could emerge.
So, Why Bitcoin?
Many people are drawn to bitcoin for its speculative upside, however bitcoin offers far more than potential capital gains. Bitcoin is a revolutionary protocol which, when judged from first principles, represents a fundamentally superior monetary system. It is voluntarily adopted, perfects the fundamental properties of money, solves gold’s physical limitations, and eliminates the centralised issuance that makes fiat currencies corruptible. Its decentralised and anti-fragile architecture protects it from political capture, while its fixed monetary rules incentivise saving, productive investment and fiscal discipline. Its permissionless and self-sovereign ethos aligns with protecting life, liberty and property, which in turn shifts incentives toward voluntary cooperation instead of coercion. Crucially, bitcoin achieves this without requiring a central authority, providing humanity a potential offramp from the perpetual cycle of monetary capture, debasement, and social upheaval. The consequences therefore extend far beyond money itself. Since money coordinates human action, a sounder money creates sounder economic incentives: favouring productivity, responsibility, cooperation and saving, over privilege, immunity, coercion and leverage. Bitcoin is therefore not just a speculative asset, it is a functionally, technically, economically, and ethically sound monetary foundation upon which a freer, more prosperous and resilient civilisation could emerge.
Bitcoin First Principles
Understanding Bitcoin requires thinking from first principles across many disciplines. Here are some good places to start.